


July is supposed to be a month for trailer suppliers to take a vacation and try not to sweat the numbers. Fleets have typically made their calls for the year, manufacturers are quietly working down backlog, and nobody’s placing big trailer orders. That’s the pattern, every year, like clockwork.
This has not been like most years, and that’s a good sign.
The Numbers Behind an Unusual July
Preliminary data from ACT Research, released Aug. 18, showed U.S. trailer orders hit 15,900 units in July. That’s up 97% from a year earlier and 18% over June, in what’s normally the weakest ordering month on the calendar. Jennifer McNealy, ACT’s director of commercial vehicle market research, didn’t hide her surprise.”
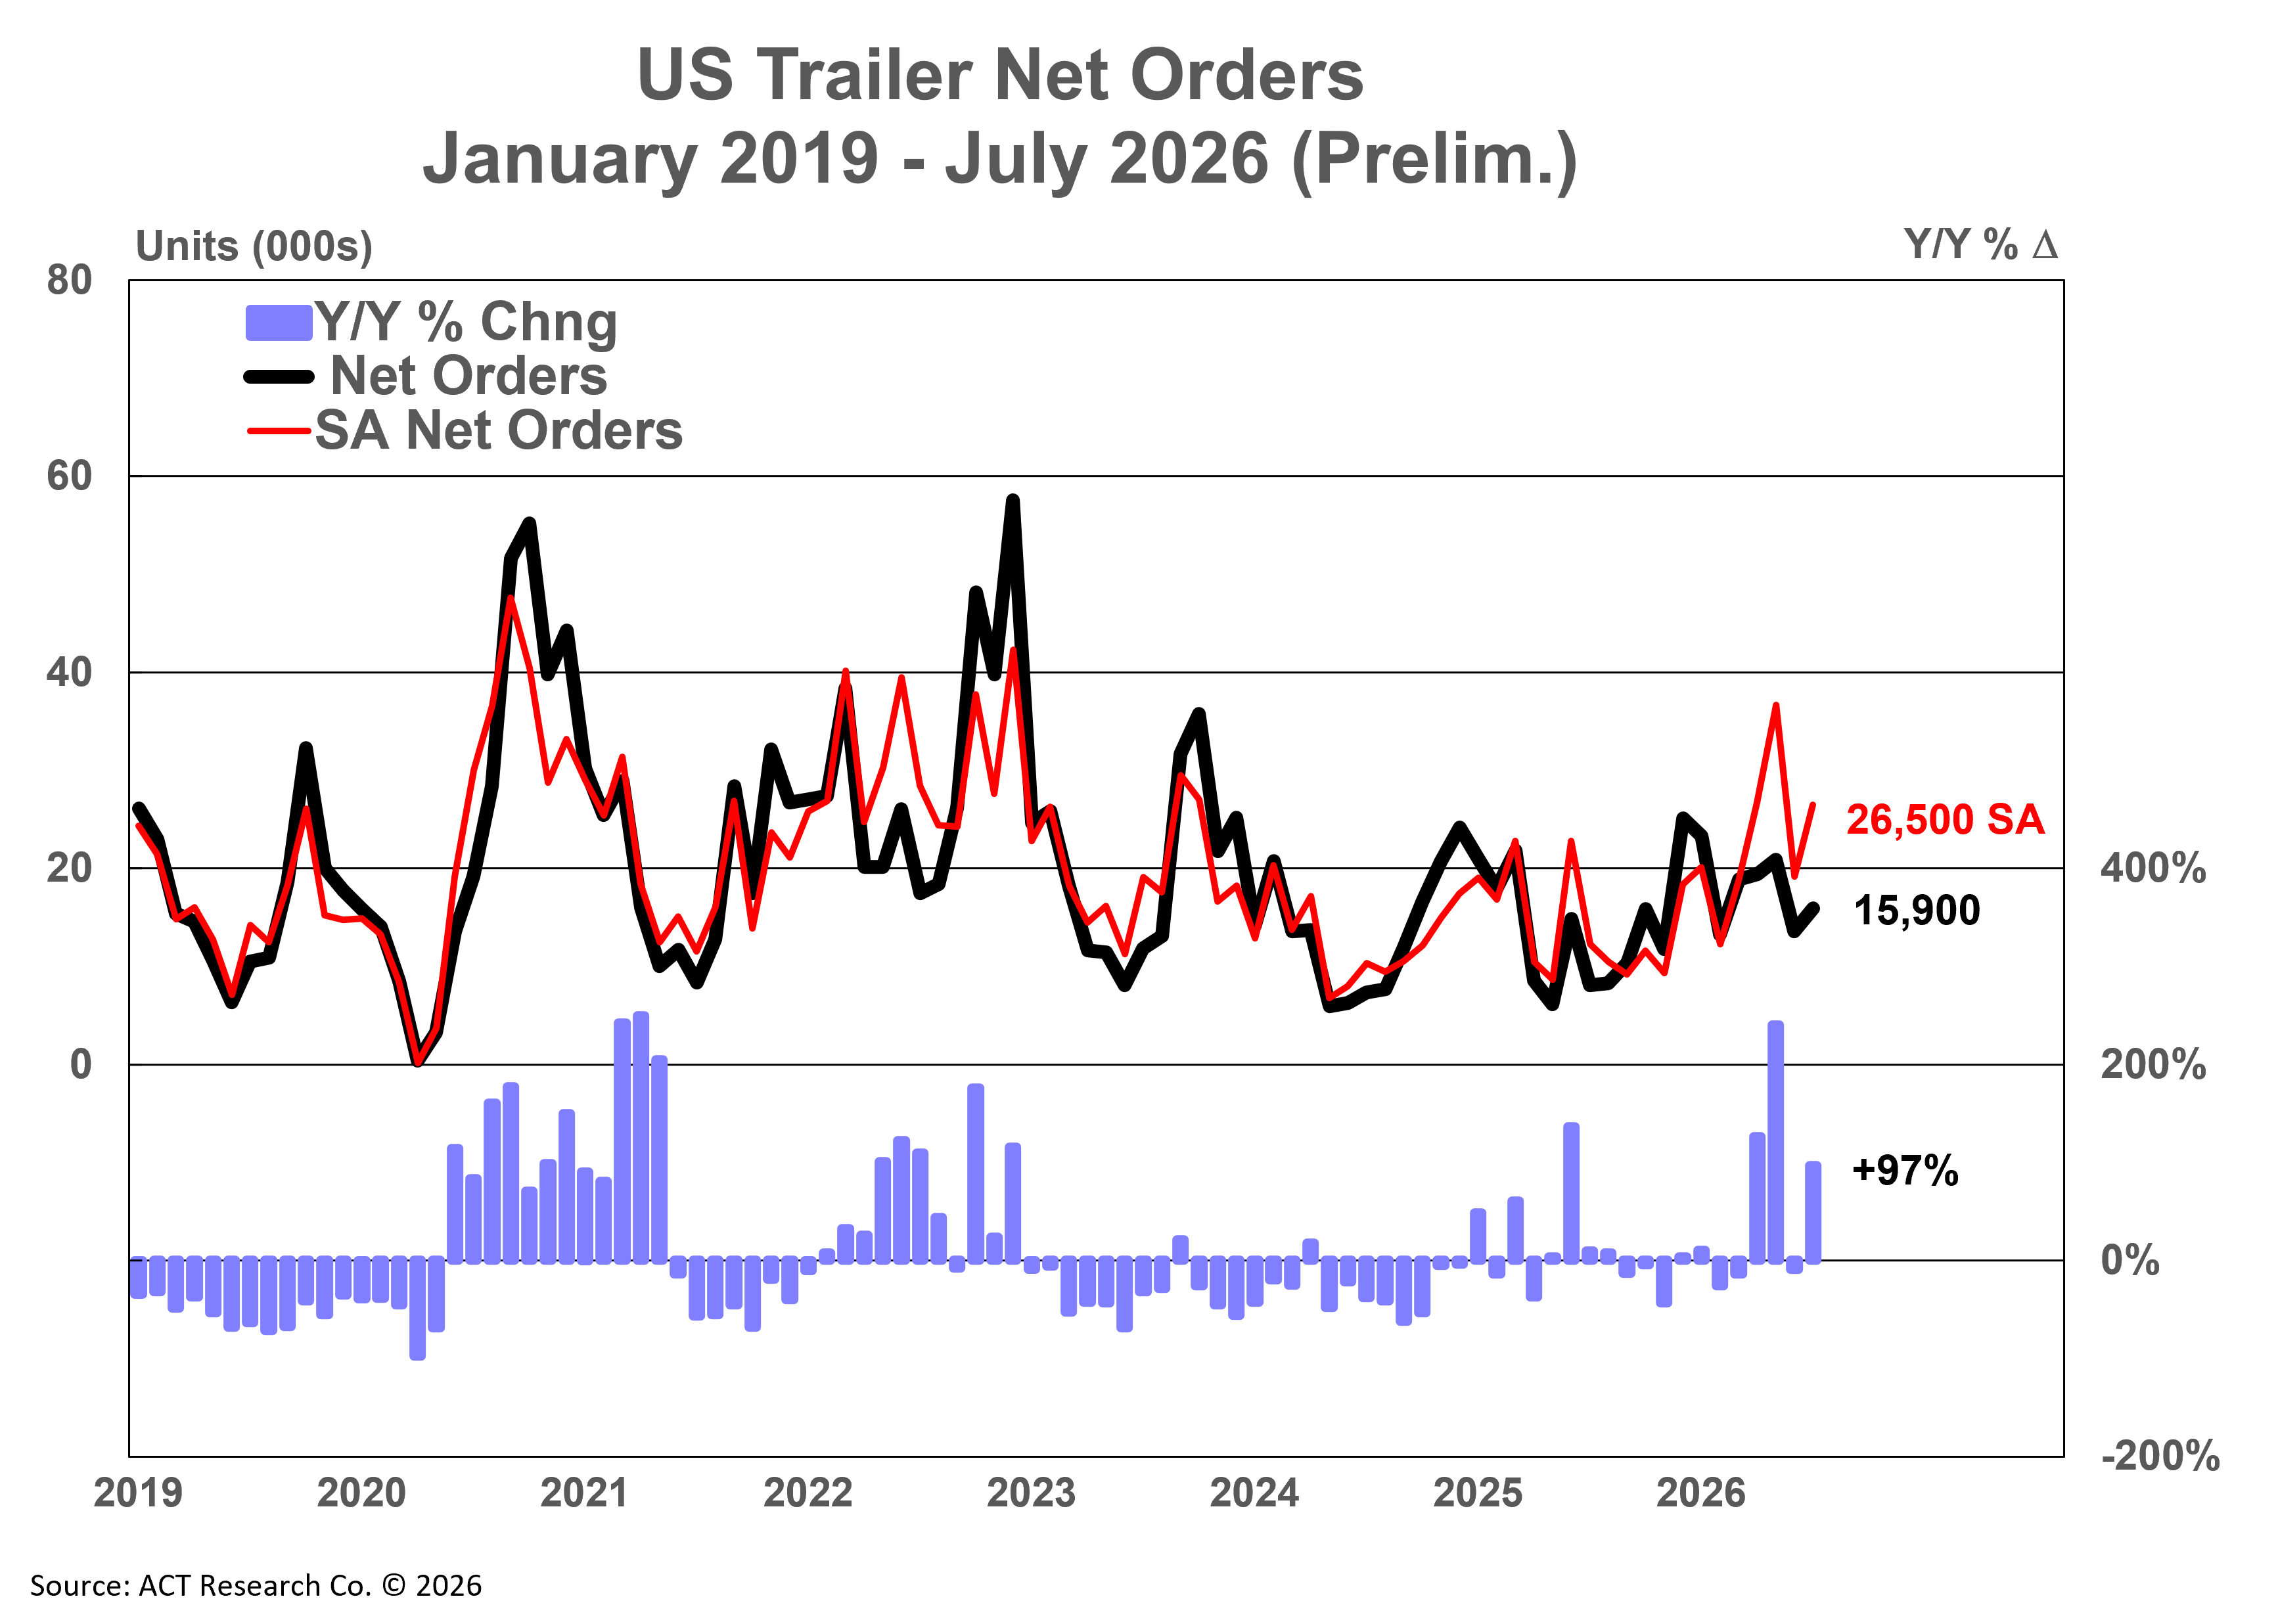
Typically, July is the weakest net order month of the annual ordering cycle,” she said. “That said, this year’s cycle has been anything but ordinary.”
McNealy noted the order strength that usually kicks in around September or October didn’t show up until December this past cycle, and it’s been running hot and out of step ever since.
Why Fleets Are Buying Now
Three things are driving it, according to OEMs surveyed by ACT:
1.
Fleets ordering ahead of tariff-related price increases.
2.
Genuinely healthier long-term business conditions.
3.
A wave of pent-up replacement demand after a few brutal years for carriers.
That last one matters most for anyone who’s been running an aging trailer fleet through a freight recession. There’s only so long you can defer maintenance and delay a purchase before the math flips back toward buying new.
McNealy was careful to add a note of caution too. The surge is “premature in terms of 2027 order timing,” and some purchasers are still holding back, weighing the cost of a new trailer against repairing an old one. Translation: don’t mistake one hot month for a boom. But don’t ignore it either.
What a Stronger Trailer Market Signals for Carriers
Rising trailer orders tend to track rising confidence in freight rates, and rates have been climbing after a long, ugly stretch. ATRI’s benchmarking data already showed operating costs hitting a record $2.336 per mile this year, so any signal that carriers are willing to invest in new equipment, rather than just squeezing more life out of what they’ve got, is worth paying attention to.
Alabama’s Fleets Are Watching the Same Signals
Alabama’s trucking economy runs on a mix of large carriers and small operators, many of whom have spent the last few years nursing aging trailers through a soft market. A stronger equipment cycle means safer, newer iron on I-65 and I-20, and it means Alabama carriers finally have room to plan instead of just survive.


